The Bank of Ghana (BoG) has started testing cross-border digital payment systems with Rwanda and Nigeria to reduce transaction costs and improve payment interoperability across Africa.
The project consists of testing interoperability among central bank digital currencies (CBDCs), stablecoins, bank accounts and mobile wallets with the three countries.
It is expected to help improve trade, remittances and payments among African businesses, particularly small and medium-sized enterprises (SMEs).
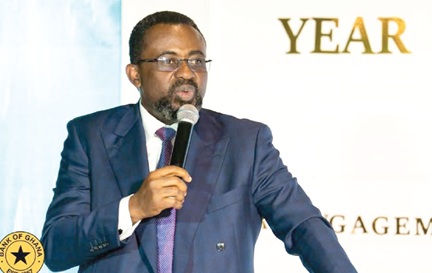
Speaking at a high-level event yesterday on digital innovations in payments during the annual meetings of the International Monetary Fund (IMF)/World Bank in Bangkok, Thailand, the Governor of BoG, Dr Johnson Pandit Asiama, stated that cross-border payments in Africa still cost more than eight per cent, as many transactions continued to pass through correspondent banks outside the continent.
“Too many payments between African countries still pass through correspondent banks outside the continent, and the cost remains above eight per cent, well short of the three per cent target.
“The Bank of Ghana aims to move the pilot projects into live services, building on existing infrastructure such as the Pan-African Payment and Settlement System (PAPSS), which has already been extended to mobile wallets along the Ghana–Nigeria corridor,” he said.
High-level event
The Joint AFR-MCM High-Level Event on Digital Innovations in Payments: Sub-Saharan Africa Future Agenda was held at the Queen Sirikit National Convention Centre in Bangkok, as part of the IMF and World Bank Group Annual Meetings.
Organised by the IMF’s African Department and Monetary and Capital Markets Department, the session brought together central bank governors and financial leaders from across Sub-Saharan Africa to discuss the modernisation of the region’s financial systems.
Discussions focused on strengthening regional cooperation and upgrading core financial infrastructure, including real-time gross settlement systems, to improve liquidity management, accelerate transactions and enhance operational resilience.
Fintech licensing rules
Dr Asiama urged African countries to harmonise fintech licensing requirements to reduce the cost and duplication associated with expanding digital financial services across borders.
He stated that Ghana’s Licence Passporting Framework with the National Bank of Rwanda was a practical model.
Dr Asiama explained that the BoG was engaging more than 10 countries to join the project.
He said a regional approach, supported by common standards for payment messaging, payee verification and fraud data sharing, would strengthen cooperation and make it easier for fintech companies to operate across African markets.
The Governor added that the BoG was ready to share its experience in interoperability, licence passporting and financial sector cybersecurity to support a safe, efficient, resilient and inclusive African payment ecosystem.
MoMo transactions
Dr Asiama stated that Ghana’s mobile money transactions exceeded one billion in August 2026 for the first time, with total value reaching GH¢519 billion, representing a 46.5 per cent increase over the previous year.
He said the milestone highlighted the rapid expansion of digital payments and the need to ensure that growing transaction volumes translated into greater financial inclusion, efficiency and stability.
The Governor stressed that strengthening consumer protection, improving interoperability and expanding access to responsible digital financial services would be critical to sustaining growth in the sector.
Financial inclusion lags
Dr Asiama said that although 81 per cent of Ghanaian adults had access to financial services, only 52.7 per cent were financially included when actual usage and service quality were considered.
He said that private sector credit remained at about 10 per cent of gross domestic product (GDP), underscoring the need for digital payment systems to support responsible savings, credit, insurance and investment.
He said the BoG was strengthening oversight of digital lenders and advancing open banking to promote competition, protect consumers and give customers greater control over their financial data.
Rise in fraud cases
Dr Asiama said that reported fraud cases in Ghana rose by 48 per cent in 2025, with almost all incidents occurring at payment service providers, although the total value at risk remained broadly unchanged.
He stressed that the trend suggested that fraud was increasingly taking the form of numerous small incidents affecting ordinary users, requiring stronger consumer education and safeguards such as payee confirmation and tighter controls on SIM replacement.
Dr Asiama added that the central bank was strengthening cybersecurity oversight through its revised Cyber and Information Security Directive, extending the Financial Industry Command Security Operations Centre (FICSOC) beyond universal banks and preparing guidance on the safe use of artificial intelligence.