Here is a question rarely asked in Ghanaian homes: Why can a government create money with a decision, while you need a title deed, a guarantor, and a bank manager’s patience to borrow a small fraction of it?
The answer is not fairness.
It is power.
Once you understand how the machine works, you can stop being its victim and start using its rules.
What government actually does
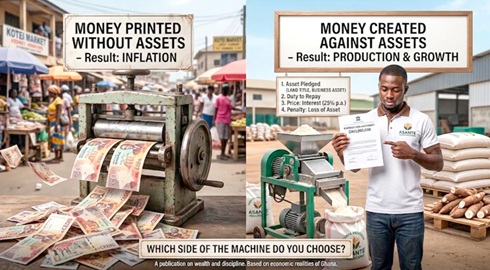
A government that prints money without assets behind it is not creating wealth.
It is creating claims on goods that already exist.
If an economy produces 100 units of goods and 100 cedis circulate, each cedi commands one unit.
Print another 50 cedis with no increase in output, and 150 cedis now chase the same 100 units. Prices rise until the arithmetic balances.
Who pays? Not the government.
You do, through the lost value of every cedi in your pocket, your savings account, and your pension.
It is a tax with no tax law, no parliamentary vote, and no name.
We call it inflation and treat it like weather.
Ghana has lived this. In 2022, the Bank of Ghana’s net claims on government rose by GH¢44.5 billion, by the bank’s own figures.
By mid-October, Bloomberg ranked the cedi the worst performer among 148 currencies it tracked, down 45.1 per cent against the dollar for the year to that date.
By December, inflation had reached 54.1 per cent.
Weimar Germany and Zimbabwe went further.
The pattern never changes: print without assets, and ordinary savers pay.
What you must do instead
Try the same thing yourself and the law answers quickly. Printing your own cedis is counterfeiting, whatever you own.
Legal tender belongs to the state.
But there is a legal route to creating new money, and it runs through collateral.
When a bank lends against land, gold, a building, or a signed trade contract, the loan itself creates a new deposit in your account.
Money that did not exist yesterday exists today. In a narrow sense, you have “printed” without working for it that day. Now notice what your money has that the government’s lacks: 1.
An asset pledged behind it. 2. A duty to repay. 3. A price: interest. 4. A penalty for failure: you lose the asset.
The government keeps none of these.
You keep all four.
That is the whole difference between financing and inflation.
The test: What do you do with it?
The loan itself is not the win.
What you do with it is.
Borrow against your land and spend the money on a wedding, a car, or a house you will not rent out, and you have bought consumption with a loan.
Nothing new is produced, the interest keeps running, and the bank is eventually paid with your property.
Governments make this exact error when they print to cover salaries and recurrent spending.
The difference is that you cannot pass the bill to millions of other people.
Put the same money into a trade, a factory, a farm, or a processing line, and the picture changes.
The venture produces goods.
Goods earn income.
Income pays the interest, repays the principal, and leaves a profit.
New money entered the economy with new goods beside it, so there is nothing extra chasing the same goods.
That is why production-backed money does not inflate, and why an economy grows only when money meets output.
The rule is simple: the return on the venture must exceed the cost of the money.
If borrowing costs 25 per cent a year and your venture earns 15, you are not building a business.
You are paying the bank to take your asset slowly.
A worked example
Take two neighbours, each owning titled land worth GH¢2 million.
Each borrows GH¢1 million at an illustrative 25 per cent interest.
That is GH¢250,000 a year in interest for both.
The first spends the loan on a house he will not rent out and a new car.
His income does not change, so he pays the interest from his salary or by selling part of his land.
Within a few years, the bank owns his collateral.
The second buys a cassava processing line and signs a supply contract.
If it earns 40 per cent, she makes GH¢400,000, pays the GH¢250,000 interest, and keeps GH¢150,000 a year.
The loan, the rate, and the collateral are the same.
Only the use of the money differs.
The practical lesson
Most Ghanaians sit on assets that earn nothing: family land with no title, gold with no certificate, stock with no records, houses with no registration.
Dead assets bring nothing back.
Before you can use the system, you must make your assets visible to it: Register and title your land.
Get your assets professionally valued and documented. Build a trade record of contracts, invoices, and bank history.
Prepare a venture plan that shows the return in plain numbers.
A bank does not lend against wealth it cannot see.
Documented, collateralised assets are what turn an owner into a creditworthy borrower.
The provocation
Here is the uncomfortable part.
In Ghana, the cost of borrowing is often too high for productive ventures to clear.
One reason is that governments borrow heavily from the same banks, which can earn safe returns lending to the state and have little reason to chase risky small businesses.
When the government takes the room, enterprise gets the leftovers.
So the question for a nation is not whether money can be created without assets.
It can, and the bill goes to savers.
The question is whether we create money against production or against political convenience.
A government that prints without assets spends your savings.
A citizen who borrows against assets and puts the money to work builds something that outlives the loan.
It is the same instrument with opposite discipline.
The money is not free.
But for those who own real assets and put them to real production, it is among the cheapest routes to wealth that any economy offers.
The only question is which side of the machine you choose to stand on.