


The country’s lower-rate cycle is forcing banks to prove that growth can survive without the unusually high interest rates of recent years.
Nine months into the year, GCB Bank PLC’s results suggest the company is finding that balance: earnings accelerated even as interest income barely moved, while lending expanded sharply alongside improving asset quality.
Between January and September, the bank’s operating income rose by 32.4 per cent year-on-year to GH¢5.70 billion, while profit before tax increased by 42.6 per cent to GH¢2.87 billion.
Profit after tax surged by 44 per cent to GH¢1.86 billion, lifting earnings per share to GH¢9.38 from GH¢6.51 a year ago.
Curiously, interest income increased by just 1.3 per cent to GH¢4.39 billion, reflecting the pressure from lower market rates.
But interest expense fell by nearly a third to GH¢816 million, allowing net interest income to rise by 14.0 per cent year-on-year to GH¢3.57 billion.
Non-funded income
The stronger lift came from non-funded income. Net fees and commissions income rose by 87.4 per cent to GH¢1.07 billion, while trading income increased by 71.6 per cent to over GH¢1.0 billion.
Together, non-funded income contributed about 37 per cent of operating income, up from about 27 per cent a year earlier.
The 10-percentage-point shift is significant in an environment where traditional interest margins are under pressure.
That shift matters because it aligns with the bank’s publicly stated push to broaden revenue sources and build a broader earnings base beyond traditional interest income.
This is vital as lower yields and tighter margins are testing the sector’s earnings resilience.
Operating efficiency improved alongside revenue growth.
Personnel, depreciation, and other operating expenses rose more slowly than income, lowering the cost-to-income ratio to about 45.1 per cent from 49.2 per cent a year earlier.
The balance sheet also expanded strongly. Customer deposits grew by 22.8 per cent to GH¢50.88 billion from December 2025, providing the funding capacity for net loans and advances to rise by 57.3 per cent to GH¢25.23 billion.
Investment securities increased by 21.1 per cent to GH¢19.80 billion, while total assets expanded by 29.0 per cent to GH¢67.62 billion.
The direction is clear. GCB is allocating more of its balance sheet to drive credit expansion and support the real economy.
That broadly mirrors the industry’s shift, back toward private-sector lending as asset quality improves.
For context, the industry’s loan book grew by 16.4 per cent year-to-August, with real growth in the private-sector credit also firming at 13.05 per cent.
Thus, GCB’s pace of loan growth has been considerably stronger than the sector average.
The Non-Performing Loans (NPLs) ratio fell to 4.8 per cent from 10.8 per cent a year earlier, compared with an industry ratio of 15.7 per cent in August, a favourable quality signal, although the pace of loan-book growth makes subsequent impairment performance equally important to watch.
Banking fundamentals
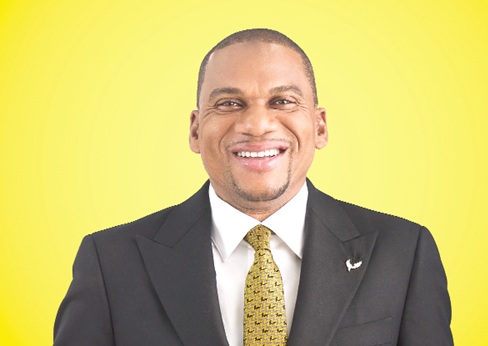
Commenting on the results, the Managing Director of GCB Bank PLC, Farihan Alhassan, said the lower-interest-rate environment was forcing banks to return to commercial banking fundamentals.
“The operating environment is demanding that banks do the hard work of banking – understand customers better, price risk appropriately, mobilise funding efficiently, and deploy capital into productive opportunities.
At GCB, we are committed to winning the right way: helping fund the ambitions of Ghanaian businesses and entrepreneurs while maintaining disciplined underwriting and strong risk standards,” he said.
He said the next priority was to build greater resilience into the bank’s loan portfolio as economic and interest-rate cycles evolved.
“Our focus is not simply on growing the loan book. It is about building a portfolio that can perform through cycles – supporting today’s growth drivers, while positioning GCB to finance the businesses and sectors that will shape Ghana’s next phase of growth.”
Mr Alhassan expressed confidence in the bank’s strategy, saying the focus remained on delivering stronger customer value and solutions that met the needs of businesses, households and the wider economy.
However, impairment charges rose to GH¢260 million, capital adequacy eased to 14.6 per cent from 16.2 per cent a year ago, and the liquidity ratio declined to 64.3 per cent from 73.4 per cent over the same period.
None of the numbers currently signals distress, but the direction matters: rapid credit growth consumes capital and liquidity, placing a premium on disciplined underwriting and balance-sheet management.
Outlook
The outlook, therefore, cuts both ways. Lower rates and resilient domestic activity should support credit demand and transaction volumes, while a broader earnings mix offers GCB more than one engine for growth.
But the same operating environment places a premium on disciplined underwriting, capital management and liquidity control.